Category: Carbon Reporting

  • UK CBAM: Your Supplier’s Emissions Data Now Has a Price

    UK CBAM: Your Supplier’s Emissions Data Now Has a Price

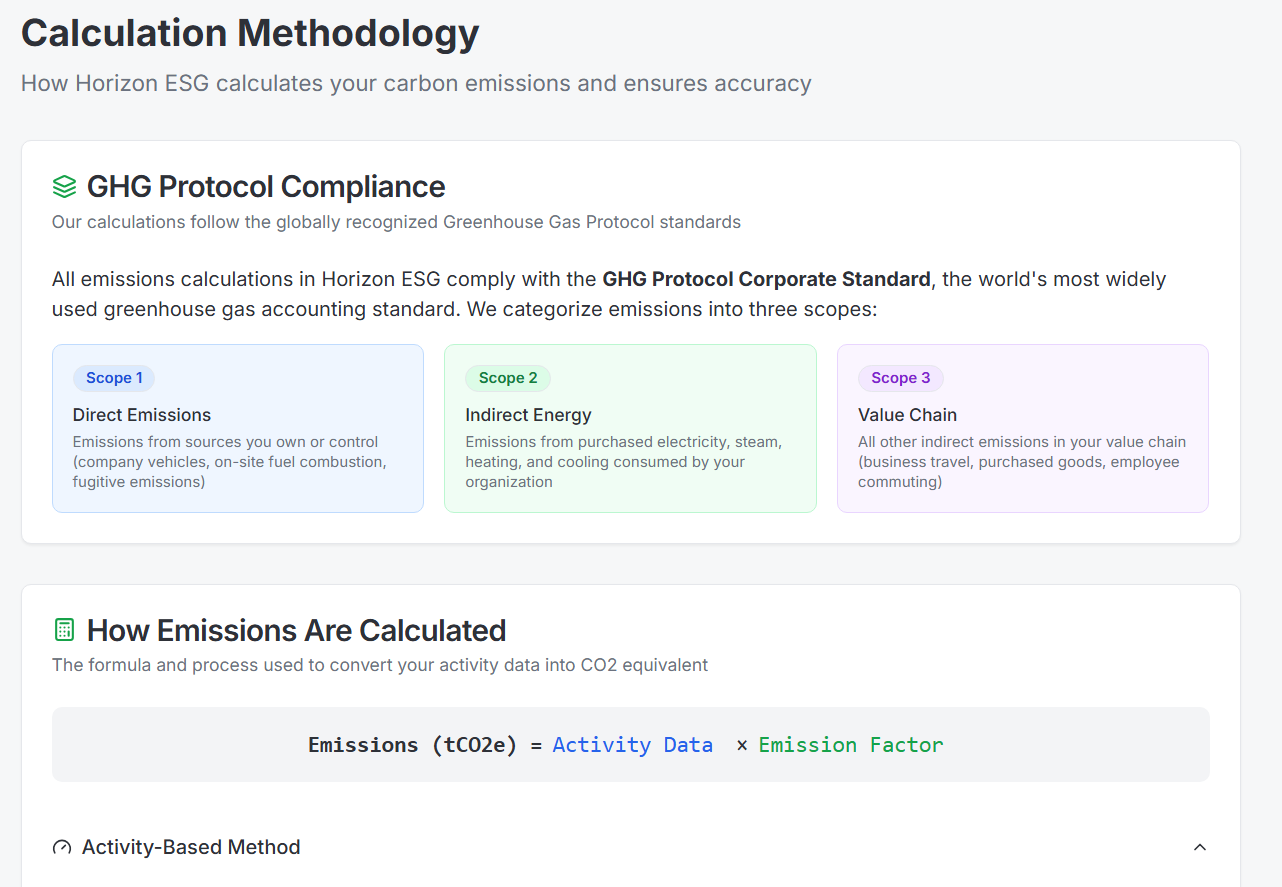
    Calculation view showing emissions as activity data multiplied by an emission factor, the same structure UK CBAM uses for embodied emissions

    Most ESG data requests arrive with a deadline set by a tender or a customer’s reporting calendar. The UK Carbon Border Adjustment Mechanism (CBAM) brings one with a tax bill attached. From 1 January 2027, every tonne of in-scope steel, aluminium, cement, fertiliser or hydrogen imported into the UK carries a carbon charge, calculated either from the overseas producer’s verified emissions or from a government default.

    On 16 October 2026, HMRC put numbers on both sides of that choice. It published illustrative CBAM rates for each sector and an updated draft of the default values, which carry a 10% markup in every sector except fertiliser. For the first time, a supplier’s actual emissions data has a direct cash value to the company buying from it.

    If you run sustainability at a UK company that imports these goods, the import team will probably come to you for that data. This post covers who pays, how the rate works, what to ask a producer for, and how to keep the evidence.


    Who pays UK CBAM

    The liable person is the importer: the business named on the customs declaration, or the business on whose behalf goods are imported. Using a freight forwarder, customs broker or agent does not move the liability to them.

    Registration is triggered by value. From 1 January 2027 you must register if either test is met:

    • Forward test: you expect to import CBAM goods worth £50,000 or more in the next 30 days.
    • Rolling test: on the first day of each month, your CBAM imports over the previous 12 months reach £50,000. Imports before 1 January 2027 do not count.

    Goods with a UK place of origin are out of scope, as are some scrap products. The UK and EU have committed to linking their emissions trading schemes, and the government says this will exempt EU-origin goods once the link is in place. Until then, check the commodity code of each product line against HMRC’s list.


    How the rate is built

    The charge is embodied emissions multiplied by a sector rate. Embodied emissions are the weight of the imported goods multiplied by an emissions intensity in tonnes of CO2e per tonne of product.

    The rate follows the UK Emissions Trading Scheme. HMRC takes the average UK ETS auction price for the previous quarter and reduces it to reflect the free allowances UK producers in that sector still receive. Its cement example uses a Q3 2026 average price of £58.15, an 87.1% free allocation share and a 2027 phase-out factor of 97.5%:

    £58.15 x [1 - (87.1% x 97.5%)] = £8.78 per tCO2e

    The illustrative rates for the other sectors are £9.69 for iron and steel, £9.79 for aluminium, £9.24 for hydrogen and £1.45 for fertiliser. Three points matter for planning:

    • These are illustrative. HMRC says they show what would apply on current data and are not forecasts. The first official rates, for January to March 2027, will be published before the end of 2026.
    • Rates are reset every quarter as the ETS price moves.
    • The phase-out factor falls over time as free allocation is withdrawn, so the share of the carbon price passed through to importers rises. Today’s modest per-tonne rates are a starting point.

    Why the default values make supplier data worth money

    When calculating embodied emissions, an importer has two options: use the producer’s verified emissions intensity, or use the government default for that commodity code. HMRC’s notice states that “actual verified emissions data is preferable” and that defaults are designed so there is “no advantage” in using them.

    The draft defaults apply from 1 January 2027 to 31 December 2028. They are trade-weighted averages built from EU data, with a 10% markup in every sector except fertiliser. From 2029 the UK plans to move to country-specific defaults, and the markup will be reviewed then.

    A worked example

    Take 1,000 tonnes of unalloyed aluminium slab (CN 76011010). The draft default is 2.058 tCO2e per tonne. At the illustrative aluminium rate of £9.79:

    • Using the default: 2,058 tCO2e x £9.79 = roughly £20,150.
    • The markup alone: about 187 tCO2e of that figure, or roughly £1,830.
    • Using verified data: if the producer’s verified intensity were, hypothetically, 1.6 tCO2e per tonne, the charge would be about £15,660.

    Scale that across a year of shipments and a rising rate, and the case for asking producers for verified data makes itself. It is also a figure your finance director will want to see, because the difference lands in cost of goods.


    What to ask an overseas producer for

    A number in an email will not do. To report actual emissions, you must hold evidence that the data has been verified. If you cannot evidence verification, you must use the default. Ask each producer for:

    1. The installation where the goods were made, and the commodity code of each product.
    2. The emissions intensity in tCO2e per tonne, calculated under the UK CBAM system boundaries, including emissions from any precursor goods for complex products.
    3. The monitoring period. Intensity is reported per calendar year. For goods imported in 2027 you use verified 2027 data, or 2026 data if 2027 is not yet verified.
    4. A verification report or verification summary covering that intensity and period.
    5. The verifier’s details. The verifier must be independent of the installation, accredited by an eligible accreditation body to ISO 14065:2020 and ISO/IEC 17029:2019, and accredited for the right activity. A fertiliser specialist cannot verify a steel plant.

    Start the conversation now. Many producers outside the EU have never been asked for installation-level data, and verification takes time to arrange.


    Keep the evidence where the other requests live

    HMRC requires importers to keep CBAM records for six years, including the verification report behind every intensity reported, with a fixed penalty of £500 for failing to keep records. That makes CBAM evidence one more thing to file alongside the customer questionnaires, lender requests and supplier data you already handle.

    The approach that works for CBAM is the same one we set out for answering customer and lender ESG data requests: one dataset, with every figure carrying its source, period, method and approval. It also mirrors what your own customers’ assurers now expect of you, covered in what your customer’s auditor will test. For the full calendar, see our ESG reporting deadlines page.

    Horizon ESG for sustainability teams holds supplier evidence in that one record, with each verified intensity linked to its report, period and producer. Nova, the built-in assistant, drafts answers only from figures that carry their evidence, labels anything estimated, and nothing goes out until a person approves it. Your finance team gets the same record, which matters when the cost of a default shows up in their numbers; our page for finance teams explains the controls.

    If the import team has already asked you about CBAM, book a short demo and bring a supplier with you. We will show you how a verified intensity sits alongside the rest of your evidence.

    Sources: HMRC, Carbon Border Adjustment Mechanism (CBAM): illustrative CBAM rates and worked example, 16 October 2026; HMRC, The Carbon Border Adjustment Mechanism (Default Values) Force of Law Notice (Draft), updated 16 October 2026; HMRC, CBAM policy summary, updated 16 October 2026; GOV.UK guidance on the importer, registration dates, emissions intensity and record keeping for CBAM. Checked 20 October 2026. Rates and default values are draft or illustrative and may change before 1 January 2027.
  • SBTi Net-Zero Standard V2: Assurance Through the Back Door

    SBTi Net-Zero Standard V2: Assurance Through the Back Door

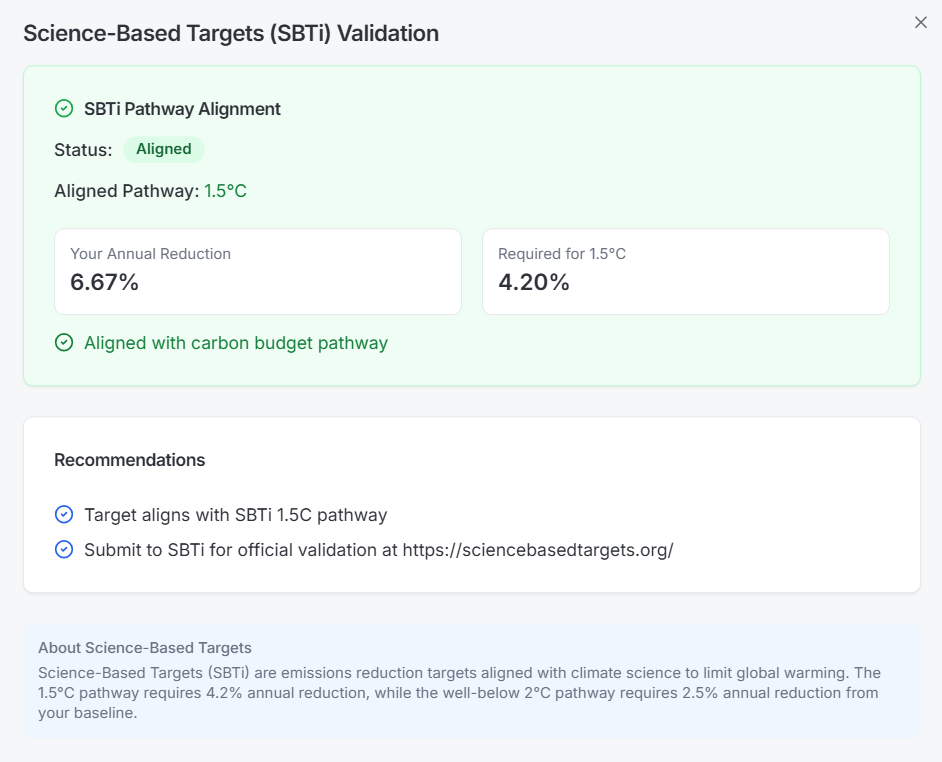
    Horizon ESG science-based targets view comparing a company's annual reduction rate with the rate required for a 1.5C pathway

    In March, a lot of finance teams crossed CSRD off the risk register. The Omnibus raised the threshold to more than 1,000 employees and more than €450m turnover, both tests together, and most mid-sized companies fell out of scope along with the assurance obligation that came with it.

    Some of those companies also hold a science-based target, and the SBTi has just rewritten its rules. Version 2.0 of the Corporate Net-Zero Standard makes independent assurance mandatory for its larger category of company, and its definition of “larger” is far wider than the one in CSRD. This is assurance arriving through a voluntary commitment. Nobody owns it, so nobody budgets for it.


    The dates

    The SBTi published Corporate Net-Zero Standard V2.0 on 11 June 2026. According to the SBTi’s own Main Changes Document, it takes effect on 31 January 2027, followed by a transition period running from Q1 2027 to Q1 2028:

    • From Q1 2027, target validation under V2.0 is available.
    • Until 31 January 2028, companies can still submit targets under V1.3.1 (and the Near-Term Criteria V5.3).
    • From 1 February 2028, every new target submission must align with V2.0.

    Companies that already hold 2030 targets are told to start setting their next cycle (2030 to 2035) under V2.0 from 2028. So the question is when you next submit, and for many companies that is sooner than the 2030 date on the current target suggests.


    Category A: why “we are too small” may not hold

    V2.0 drops the separate SME route and sorts every company into one of two categories. Category A carries the full set of obligations. You are Category A if you meet either of these tests:

    • Any country: net turnover of €450m or more, or 1,000 or more full-time equivalents.
    • High-income countries (using the World Bank classification, which includes the UK): Scope 1 and 2 emissions of 10,000 tCO2e or more, or at least two of a €25m balance sheet, €50m turnover and 250 FTEs.

    Everyone else is Category B. Three details matter for finance. Thresholds are assessed on consolidated group figures, even if your target boundary sits lower in the group. They use the average of your two most recent financial statements. Geography follows the country where the ultimate parent is incorporated.

    Compare that with CSRD. CSRD now needs 1,000 employees and €450m. Category A needs only one of them, and in a high-income country a 300-person business with €60m turnover and a €30m balance sheet qualifies. Plenty of companies that fell out of CSRD scope in March are squarely Category A.


    What Category A has to do

    Assurance, at three points in the cycle

    Criterion CNZS-C7 requires independent third-party assurance of the target base year inventory, at a minimum of limited assurance, covering Scope 1, Scope 2 and Scope 3, low-carbon electricity calculations, significant emissions-intensive activities and any other metric used to set targets. The provider must be an accredited independent third party working to internationally recognised assurance standards. The SBTi says it will set out which frameworks it recognises; in practice many providers will run these engagements under ISSA 5000, the new global assurance standard.

    Any base year recalculation must also be assured (C8.6), as must the data behind your end-of-cycle progress assessment (C37.7). The level of assurance is shown publicly on the SBTi Dashboard.

    A published transition plan

    All companies need a transition plan approved by the board. Category A companies must publish it within 15 months of target validation.

    Scope 3 targets, on a new boundary

    Near-term Scope 3 targets are required for Category A and optional for Category B. The old two-thirds coverage rule is replaced by a significance test: targets must cover every Scope 3 category representing 5% or more of categories 1 to 14 emissions, with limited named exclusions that must be reported and justified.


    The other changes worth knowing

    • Separate Scope 1 and Scope 2 targets replace the combined Scope 1 and 2 target. Scope 2 emissions targets are based on the location-based inventory, with market instruments dealt with separately under a new implementation hierarchy.
    • A target base year built on your latest comprehensive data replaces the historical base year. You can still communicate progress against an earlier year if equivalence is validated.
    • Carbon removals get detailed neutralisation rules on storage durability and double counting, plus a requirement for Category A companies to support removals from 2035.

    One point is widely misunderstood, so it is worth stating plainly: carbon credits still cannot be counted toward your Scope 1, 2 or 3 targets. V2.0 creates a voluntary Ongoing Emissions Responsibility recognition programme for credits and other climate contributions, and the standard says outcomes claimed there cannot be counted toward target implementation or netted from the inventory. Credits sit alongside reductions. They never replace them.


    From “does not apply” to an unbudgeted fee

    A typical case looks like this. The sustainability team set a near-term target in 2022 or 2023. The company is 600 people with €120m turnover, so finance correctly concluded in March that CSRD no longer applies. The next SBTi submission falls in 2028, under V2.0, as Category A.

    Because V2.0 uses your most recent comprehensive data as the base year, a 2028 submission will most likely rest on FY2027 figures. Those figures need limited assurance across all three scopes before validation. FY2027 starts in about three months for a calendar-year company, and the assurance fee and internal time are probably in nobody’s plan.

    Scope 3 is the expensive part. Limited assurance of supplier-derived data, spend-based estimates and emission factor choices tests the documentation behind every number. The practitioner checks that methods are recorded and reproducible and that estimates are labelled. Our post on the six tests an assurance provider actually runs sets out what that looks like in practice.


    What to have in place a year ahead

    • Run the category test now on consolidated, two-year-average figures, and record the result with the workings.
    • Find out when you next submit. Check the SBTi Dashboard and your commitment letter. If it is 2028 or later, plan on V2.0.
    • Treat FY2027 as a probable base year. Fix the boundary and factor sets for the year and attach evidence as data is entered.
    • Re-map Scope 3 against the 5% test and identify which categories will need targets and which exclusions you would have to justify.
    • Talk to an assurance provider this autumn about scope, level and the disclosures they see as high risk.
    • Put the fee and internal time in the FY2027 budget. Where lineage is visible, the practitioner spends less time reconstructing evidence and the fee reflects it.
    • Get the transition plan onto the board agenda, since it needs board approval and, for Category A, publication within 15 months of validation.

    For context on what validation requires under today’s rules, see what SBTi validation actually requires.

    One last point. The SBTi inventory, the numbers in customer questionnaires and any figures in the annual report should come from the same evidenced dataset. When they come from three spreadsheets, the assurance provider will find the gaps before you do.

    Horizon ESG holds datapoint-level lineage, factor source and version on every calculation, labelled estimates, an immutable change log and enforced separation between preparer and approver, the controls a limited assurance engagement on a base year inventory will test. Horizon ESG for finance teams sets out how that works for a controller or CFO. If an SBTi submission is on your horizon, book a short demo and ask us to trace a Scope 3 figure back to its source, live.

    Sources: SBTi Corporate Net-Zero Standard V2.0 (June 2026) and Main Changes Document (11 June 2026); SBTi Corporate Net-Zero Standard page, checked 22 September 2026.

  • SB 253 Deadline: Three Reliefs Buried in CARB’s Redline

    The nearest binding climate-reporting deadline anywhere in the world is not in Brussels. It is 10 November 2026, when the first Scope 1 and Scope 2 disclosures under California’s SB 253 fall due — around fourteen weeks from now. And the document that decides how hard that filing will actually be was published on 27 July, arrived as a redline, and has been read by almost nobody outside the law firms.

    On that date the California Air Resources Board published its modified initial regulation implementing SB 253 and SB 261, and opened a 15-day public comment period closing 11 August 2026. Most coverage led with the deadline deferral — from 10 August to 10 November — already known since June. Further down the text sit three first-year concessions that materially change what an in-scope company has to produce this year, each the kind of provision that vanishes in a press-release summary.


    First, what this document is — and isn’t

    It is a modified text out for comment, not a final rule: it still has to clear the comment period and review by the Office of Administrative Law before it binds. Treat what follows as a strong signal of CARB’s intent rather than settled law — while not planning a fourth-quarter data sprint as though none of it exists.

    The scope test is unchanged: companies with total annual revenue above $1 billion that do business in California. The first report covers FY2025 Scope 1 and Scope 2 emissions, due 10 November 2026.


    Relief one: the 5 December 2024 data cut-off

    For initial reporting only, a company may rely on information it possessed, or was already in the process of collecting, as of 5 December 2024.

    Read that slowly, because it inverts the instinct most teams are acting on. The benchmark for your first California filing is not the best inventory you could assemble by November — it is the inventory your systems were already producing more than eighteen months ago. If utility data for a set of leased sites was never metered separately in 2024, CARB’s text does not require you to reconstruct it now.

    The practical effect is that the sensible first-year project is narrower than most teams have scoped it. Rather than retro-instrumenting every site, the work is to establish what you genuinely held at that date, report on that basis, and document the boundary clearly enough that it survives a later question. That is a governance and evidence exercise more than a measurement one — the same discipline that applies whenever estimated data is good enough to report: state the method, state the limitation, keep the trail.

    What it does not do

    It is explicitly a first-year provision. It does not waive the obligation to file, and it does not carry into the 2027 cycle — by which point the expectation is a properly built inventory. Nor is it self-executing: relying on it means being able to evidence what you held and when. A company that quietly uses the relief without recording why has taken the risk without the protection.


    Relief two: intercompany revenue is out of the $1 billion test

    The modified text clarifies that revenue transmitted between a parent and a subsidiary, or between different parts of the same company, is not counted as revenue when applying the $1 billion threshold.

    This matters more than it sounds. Groups running captive distribution entities, internal manufacturing transfers or centralised procurement can show gross figures well above the threshold that are substantially internal turnover. An entity that looked comfortably in scope may not be in scope at all once genuine third-party revenue is isolated.

    If your scoping decision was made in 2025 on a quick read of group revenue, re-run it before you commit a reporting budget. Threshold questions are cheap to answer now and expensive to answer in November.


    Relief three: one consolidated report for the group

    The modified regulation permits a parent company to submit a consolidated report covering its in-scope subsidiaries, rather than requiring each entity to file separately. Fees are still assessed on a per-company basis, so this is an administrative simplification rather than a financial one.

    The value is in coherence. One filing means one organisational boundary, one consolidation approach, one set of emission factors and one assurance conversation — instead of several subsidiary submissions that anyone can lay side by side and find inconsistent.

    One caveat: the consolidated boundary you use for California should reconcile to the consolidation approach in your GHG inventory and to whatever you publish elsewhere. A boundary chosen for administrative convenience creates a discrepancy you will spend years explaining.


    What the reliefs don’t touch

    Scope 3 arrives in 2027 — but only five categories

    CARB has signalled a phased approach for the 2027 cycle, with initial Scope 3 reporting focused on five commonly reported categories rather than all fifteen: purchased goods and services, fuel- and energy-related activities, waste generated in operations, business travel, and employee commuting, with flexibility around de minimis categories.

    That is a genuine sequencing instruction, and it is unusual to be handed one. Four of the five can be built largely from data your finance and HR systems already hold. The fifth — purchased goods and services — takes a year, because it depends on spend categorisation and supplier engagement rather than a single system. That is your critical path.

    Assurance is coming, on a proposed schedule

    CARB’s proposals introduce limited assurance over Scope 1 and Scope 2 from qualified independent providers, recognising several standards families — AICPA, IAASB and ISO-based frameworks among them — with a move toward reasonable assurance signalled around 2030. The detail is still in play; the direction is not. If you have been through limited assurance under CSRD, you know the real cost is not the auditor’s fee. It is having evidence attached to every number.

    SB 261 is still enjoined — SB 253 is not

    These two laws are routinely discussed together but sit in very different positions. The Ninth Circuit enjoined enforcement of SB 261, the climate-risk reporting law for companies above $500 million in revenue, on 18 November 2025 pending appeal; oral argument was heard on 9 January 2026 and, at the time of writing, no merits decision has been published. SB 253 was not enjoined. Its deadline is live. Anyone who paused California work on the strength of “the courts blocked it” has confused the two.


    Fourteen weeks: a working sequence

    • Re-run the threshold test on third-party revenue only, excluding intercompany turnover, and write down the answer with its basis.
    • Establish your 5 December 2024 position. What Scope 1 and Scope 2 data did you hold, or have in collection, at that date? That list defines the scope of your first report.
    • Decide the filing structure — consolidated at parent level or entity by entity — and check the boundary reconciles to your existing inventory.
    • Comment by 11 August if any of the three provisions is ambiguous for your structure — the last low-cost way to influence the text.
    • Separate the FY2025 filing from the 2027 build. Different projects, different standards of rigour; merging them is how first-year filings become nine-month programmes.
    • Start purchased goods and services now, not in 2027. It is the only one of the five categories that cannot be delivered in a quarter.

    The pattern is familiar. As we argued when the SEC’s climate rollback failed to free US multinationals, federal deregulation has not reduced disclosure obligation — it has moved it to states and to Europe, where the timetables are statutory and the reliefs are technical rather than political.


    If 10 November is on your calendar, the question is not how much data you can gather — it is how much you can evidence. Horizon ESG helps teams collect emissions data once, keep the audit trail attached, and report it against SB 253, CSRD and ISSB without rebuilding the inventory each time. Book a free demo.

  • Data Centres Just Became an ESG Disclosure Risk

    On 14 July 2026, New York became the first US state to slam the brakes on data centre construction. Governor Kathy Hochul signed an executive order barring the Department of Environmental Conservation from issuing discretionary permits for new data centres above 50 MW of power demand for up to a year, while regulators write comprehensive standards from scratch. The trade press read it as an energy-and-AI story. For sustainability teams, it is something else entirely: the moment data centre energy stopped being a line in your Scope 2 footnote and became a strategic disclosure risk your climate reporting has to describe.

    If your business runs a material digital estate — and in 2026 most do — this is the clearest signal yet that compute energy is moving from an efficiency talking point to a permitting, siting, and transition-risk question. The reporting frameworks you already comply with anticipated this. Most disclosures have not caught up.


    What New York actually did

    The order does not ban data centres. It pauses discretionary environmental permitting for the largest facilities — those drawing more than 50 MW, roughly the scale of a hyperscale or large colocation site — for up to twelve months while the state builds a standing regulatory regime. The stated concern is straightforward: surging AI and cloud demand is loading the grid faster than New York can plan for, and the existing permitting process was never designed to weigh that.

    The specifics matter less than the precedent. A US state has now formally treated large-scale compute as an environmental externality worth constraining. That is exactly the kind of policy shift that climate-risk frameworks classify as a transition risk — a change in the regulatory environment that alters the cost, feasibility, or location of your operations. And New York is unlikely to be the last mover; when one jurisdiction sets a template, disclosure-conscious investors start asking every data-centre-intensive issuer the same questions.


    Why this is a disclosure problem, not just an energy one

    Here is the disconnect. Most companies account for data centre electricity as a Scope 2 emissions figure — a number to be measured, reduced, and reported. That framing is correct but incomplete. It captures what your compute emitted last year. It says nothing about whether you can build, power, or expand that compute next year.

    From Scope 2 line item to transition risk

    A permitting moratorium changes the calculus. If a company’s growth assumes new data centre capacity in a jurisdiction that has just paused approvals, that assumption now carries policy risk — potential delay, higher cost, or forced relocation. Under a climate-risk lens, that is a material forward-looking exposure, not a historical emissions total. The same logic extends to grid connection queues, rising industrial power prices, and local opposition, all of which are tightening in the markets where compute demand is highest.

    The physical-risk angle teams forget

    Transition risk is only half the picture. Large data centres are also water-intensive — cooling can consume millions of litres a year — and they concentrate that demand in specific locations. That exposes them to physical climate risk: drought, heat stress, and water-access restrictions that can throttle operations regardless of how clean the power is. A disclosure that reports Scope 2 emissions but ignores where the facilities sit and what they depend on is telling investors half a story.


    What ISSB S2 and ESRS E1 already require

    None of this requires a new rule. The two frameworks most reporters are already inside — IFRS S2 from the ISSB, and ESRS E1 under the CSRD — both demand exactly the forward-looking narrative that data centre exposure calls for.

    • IFRS S2 requires disclosure of the climate-related risks and opportunities that could reasonably affect your prospects, split into transition and physical risk, plus how they feed strategy, financial planning, and resilience under different scenarios. A permitting-constrained compute footprint is a textbook example of what S2 expects you to surface.
    • ESRS E1 requires a transition plan, disclosure of material physical and transition risks, and reporting of energy consumption and mix alongside gross Scopes 1, 2, and 3. The connective tissue between your energy dependency and your strategic resilience is precisely what E1’s risk disclosures are for.

    In other words, the standards already ask the question. New York just made it concrete. For teams still treating climate risk and carbon accounting as separate exercises, this is the argument for joining them up — a theme we explored in our look at how TCFD and CSRD climate disclosure align.


    What a defensible disclosure looks like

    Most current data centre disclosure is boilerplate: an efficiency metric, a PUE figure, maybe a renewable-energy commitment. That is not what a climate-risk framework is asking for. A disclosure that would survive scrutiny does four things:

    • Locates the exposure. Identify where your material compute capacity sits — owned, colocated, or cloud — and flag jurisdictions where permitting, grid access, or water stress is tightening. Generic group-level statements are not enough.
    • Connects energy to strategy. Explain how future capacity needs interact with transition risk. If growth depends on new facilities, say what a permitting delay would mean for the plan.
    • Treats water as a risk, not a footnote. Disclose cooling water dependency in high-stress locations as a physical risk with operational consequences, not just a sustainability metric.
    • Quantifies where it can. Move from “we are committed to efficiency” to ranges, timelines, and scenario-tested impacts. Frameworks reward specificity and penalise vagueness.

    The reporting teams that get ahead of this will not be the ones with the lowest emissions. They will be the ones who can show investors they understand where their digital infrastructure is exposed — and have a credible plan for it. Reliable, location-aware energy and emissions data is the foundation for that; measuring your Scope 1, 2 and 3 footprint accurately is the first step, but connecting it to forward-looking risk is what turns a number into a disclosure.


    Turning compute energy into an audit-ready climate disclosure starts with data you can trust. Horizon ESG helps reporting teams link emissions, energy, and transition-risk narrative in one place — so when the next New York arrives, your disclosure is already ready. Book a free demo to see how.

  • Setting Science-Based Targets: What SBTi Validation Actually Requires

    By Sai Shankar, Guest Author

    Announcing a Net Zero commitment is now commonplace. Getting that commitment validated as a science-based target is a considerably more involved exercise, and it is where many organisations discover that their emissions data, methodology, and internal alignment are less complete than they had assumed.

    The Science Based Targets initiative provides the most widely recognised framework for setting corporate climate targets that are consistent with the goals of the Paris Agreement. Its validation process serves as an independent check on whether a target is credible, whether the underlying inventory is fit for purpose, and whether the commitment is anchored in a defensible pathway.

    What SBTi Is and Why It Matters

    The Science Based Targets initiative is a partnership between CDP, the United Nations Global Compact, the World Resources Institute, and the World Wide Fund for Nature. It sets criteria for corporate emissions reduction targets, validates targets submitted by companies, and publishes those validations for public reference.

    A validated SBTi target is increasingly a market expectation rather than a differentiator. It is referenced by:

    • Investor stewardship teams assessing portfolio company climate credibility
    • Customers embedding supplier decarbonisation requirements into procurement decisions
    • Ratings agencies and ESG data providers
    • Regulators and policymakers evaluating corporate transition claims

    An announcement of intent, without SBTi validation, no longer carries the same weight it did a few years ago.

    The Overall Structure of an SBTi Target

    Under the SBTi framework, a company committing to science-based targets is required to set:

    • Near-term targets: covering a period of typically 5 to 10 years from the base year, addressing Scope 1 and 2, and Scope 3 where it is material
    • Long-term targets: setting the level of decarbonisation required to reach Net Zero, typically by 2050 or earlier depending on the sector and the standard applied
    • Net Zero commitment: a formal statement of the year in which the company will reach Net Zero across the required scopes

    The near-term and long-term targets are not alternatives. Both are required under the Corporate Net-Zero Standard, and the near-term target is the immediate accountability mechanism.

    Scope 3: The Requirement Most Companies Underestimate

    SBTi requires the setting of a Scope 3 target where Scope 3 emissions represent 40 per cent or more of the company’s total emissions. In practice, this threshold captures the majority of companies in almost every sector outside heavy industry.

    The Scope 3 target must cover at least two-thirds of total Scope 3 emissions in the near term. This is where the operational challenge sits. For many companies, Scope 3 accounts for 80 to 95 per cent of the total inventory, and the largest categories are often supply chain (Category 1) and use of sold products (Category 11).

    Setting a defensible Scope 3 target therefore requires:

    • A reasonably complete Scope 3 inventory across the material categories
    • Sufficient data quality to establish a credible base year
    • A pathway that reflects real levers, not aspirational reduction assumed to occur in the future
    • Clarity on which categories are included and excluded, with reasoning

    Companies that submit an SBTi validation with a weak Scope 3 foundation frequently need to withdraw and resubmit. Getting the inventory right before targeting is faster than the reverse.

    The Validation Process

    The SBTi validation process moves through five broad stages:

    • Commit: the company signs a commitment letter, publicly declaring intent to set a science-based target
    • Develop: the company develops emissions reduction targets consistent with the SBTi criteria
    • Submit: the company submits its targets to SBTi for formal validation, along with the required supporting information
    • Communicate: once validated, the company communicates its targets publicly and inputs them into the SBTi target dashboard
    • Disclose: the company reports progress against its targets annually and provides an updated GHG inventory

    Validation is a paid service, with the fee tied to company size. It is not a rubber stamp. Validators assess the target ambition, the inventory boundary, the methodology, and the internal consistency of the submission. Rejections and requests for resubmission are common.

    What SBTi Actually Reviews

    The specifics of the review vary by company and target type, but common areas of focus include:

    1. Base Year Selection

    The base year must be recent and representative. Choosing a base year in which emissions were unusually high, for example due to a one-off event, is likely to be challenged. The base year inventory must be complete, calculated to a consistent methodology, and recalculable if the company boundary changes.

    2. Target Ambition

    Near-term Scope 1 and 2 targets must be consistent with limiting warming to 1.5 degrees Celsius, which for most sectors means a minimum linear annual reduction of 4.2 per cent from the base year. Scope 3 targets may be aligned with either 1.5 degrees or well below 2 degrees, depending on the target type and sector.

    3. Boundary and Coverage

    The target must cover at least 95 per cent of Scope 1 and 2 emissions across the corporate boundary. Any exclusions must be justified. For Scope 3, the two-thirds coverage requirement applies as noted above.

    4. Methodological Consistency

    Emissions must be calculated using recognised methodologies, typically the GHG Protocol Corporate Standard and Corporate Value Chain Standard. Inconsistent application, undocumented emission factors, or unclear boundary decisions are common reasons for rework.

    5. Sector-Specific Guidance

    Certain sectors, including power, financial institutions, forest, land and agriculture, and others, have specific SBTi guidance and methodologies. A submission that does not follow the applicable sector guidance will not be validated.

    Recent Evolution: The Corporate Net-Zero Standard

    SBTi’s Corporate Net-Zero Standard sets the requirements for corporate Net Zero targets. A revised version of the standard has been under consultation, with proposed changes including clearer treatment of Scope 3, changes to the role of carbon removals and offsets, and refined requirements for hard-to-abate sectors. Version 2.0 was published on 11 June 2026 and takes effect on 31 January 2027. Our guide to what SBTi Net-Zero Standard V2 changes covers the new company categories and the mandatory assurance that comes with them. The Scope 3 coverage figures in this article follow V1.3.1.

    Companies currently developing or refining SBTi targets should track the standard’s evolution closely. Targets validated under one version of the standard may need to be revisited when a subsequent version becomes effective, particularly where the treatment of Scope 3 or carbon removals changes materially.

    Where Companies Get Stuck

    The most common failure modes we see in SBTi target-setting programmes:

    • Incomplete Scope 3 inventory: committing to a target before the underlying Scope 3 data foundation is in place, leading to rework and delays
    • Base year issues: selecting a base year without documenting why it is representative, or without a clear restatement policy for subsequent boundary changes
    • Overreliance on offsets in the pathway: assuming that offsets or removals will close the gap, when SBTi requires reductions to come primarily from operational and value chain decarbonisation
    • Sector guidance overlooked: submitting targets without applying the applicable sector-specific methodology
    • No internal governance: targets set by the sustainability team without formal approval by finance, operations, and executive committees, leading to weak accountability and slow progress
    • Progress reporting deferred: committing to annual disclosure but not building the underlying system to produce it, so that year-on-year reporting becomes a fire drill

    How Horizon ESG Supports SBTi Target-Setting and Tracking

    Horizon ESG’s Targets and Baselines module and Emissions Pathway module are designed to support the full lifecycle of a science-based target. Teams can:

    • Establish a base year inventory with structured methodology documentation
    • Model reduction pathways aligned with 1.5 degree and well below 2 degree scenarios
    • Structure Scope 3 targets with defined category coverage and inclusion rules
    • Track annual performance against near-term and long-term targets in a single view
    • Manage restatement of base year figures where boundary changes occur
    • Generate progress disclosures consistent with SBTi reporting expectations

    The result is a target-setting and progress-tracking process that is defensible during validation and sustainable over the ten-year performance horizon that SBTi requires.

    A Practical Starting Point

    If SBTi validation is on the roadmap but the Scope 3 inventory is not yet complete, sequence the work. Building the inventory first, and using it to inform the target, produces a stronger submission than the reverse.

    Book a free demo of our ESG reporting software to see how Horizon ESG supports the full path from inventory to target-setting to annual progress reporting.

  • Scope 1 Reporting: Mistakes That Fail Audits 2026

    Scope 1 Reporting: Mistakes That Fail Audits 2026

    What are the main challenges of Scope 1 emissions reporting?

    Scope 1 emissions are direct greenhouse gas releases from sources owned or controlled by the reporting organisation. Under the GHG Protocol, this covers stationary combustion (boilers, furnaces), mobile combustion (fleet vehicles), process emissions (chemical reactions), and fugitive emissions (refrigerant leaks). Despite being considered the most straightforward scope to report, Scope 1 presents significant challenges around boundary definition, measurement accuracy, and source identification.

    Source TypeExamplesCommon ChallengeData Source
    Stationary combustionBoilers, furnaces, generatorsMetering gaps across sitesFuel invoices, meter readings
    Mobile combustionFleet vehicles, company carsGrey fleet boundary definitionFuel cards, mileage logs
    Process emissionsChemical reactions, cement productionComplex stoichiometric calculationsProduction records, engineering models
    Fugitive emissionsRefrigerant leaks, gas systemsDetection and quantificationMaintenance logs, top-up records

    Horizon ESG Playbook

    Scope 1 Reporting: The ‘Easy’ Scope That Rarely Is

    Scope 1 emissions are often positioned as the easy starting point for carbon reporting. They’re direct, operational, and—on paper—within your control. In reality, Scope 1 is where reporting often becomes fragile first, because the activity data underneath it is operationally messy, fragmented, and inconsistent.

    Why “Direct Emissions” Are Rarely Simple

    Scope 1 reporting emissions are often positioned as the easy starting point for carbon reporting. They’re direct, operational, and—on paper—within your control. In reality, Scope 1 is where reporting often becomes fragile first, because the activity data underneath it is operationally messy, fragmented, and inconsistent.

    Fuel Combustion: When the Numbers Don’t Line Up

    Stationary fuel data rarely lives in one place. A retailer may have monthly gas bills, weekly sub-meter readings, and quarterly bulk diesel invoices—each in different units and time periods. When reporting season arrives, sustainability teams are left reconciling operational reality with financial expectations.

    The challenge: converting inconsistent, site-level data into a defensible annual emissions figure without guesswork.

    Company Vehicles: Ownership Is Not Always Obvious

    Fleet emissions become complex once leasing, grey fleets, and mileage claims enter the mix. One organisation discovered halfway through reporting that sales mileage claimed via expenses had never been included, while leased vans were counted twice by different teams.

    The challenge: defining what is in scope—and proving it—when vehicle data is split across HR, fleet providers, and finance systems.

    Refrigerants: Small Data, Outsized Impact

    Facilities teams often track refrigerant top-ups purely for maintenance. What’s missed is that a single kilogram of certain refrigerants can equal several tonnes of CO₂e. In one case, a minor data correction triggered a material year-on-year emissions spike that no one could easily explain.

    The challenge: limited visibility combined with extremely high emission factors.

    Process Emissions: Operational Data Lost in Translation

    Manufacturing sites track throughput in operational terms—batches, tonnes, run hours—rarely aligned to ESG reporting needs. Engineering data is accurate, but not ESG-ready.

    The challenge: translating technical data into emissions without oversimplifying or losing credibility.


    Best Practice: Treat Scope 1 Reporting Like an Operational Control Process

    Leading organisations manage Scope 1 reporting emissions with the same discipline as safety, cost, or uptime: clear ownership, consistent data models, transparent assumptions, and systems that reflect how operations actually work.

    How this adds value across roles

    • For the operational manager (data owner):
      Clear inputs, fewer ad-hoc requests, and emissions metrics that align with how sites are already managed—reducing disruption and rework.

    • For the ESG manager (process owner):
      Reliable, traceable data with known quality levels, enabling smoother reporting cycles and fewer late-stage escalations.

    • For the CSO and CFO (board reporting):
      Confidence. Numbers that reconcile, variances that can be explained, and a clear narrative that stands up to scrutiny.

    The takeaway:
    When Scope 1 reporting is built around operational reality, it stops being a reporting risk—and becomes a credible, repeatable foundation for everything that follows.

    What This Means for You
    If You’re in Operations or Facilities

    Scope 1 reporting often feels deceptively simple — fuel in, emissions out. In practice, they’re shaped by incomplete data, mixed fuel sources, ageing assets and operational workarounds that don’t show up neatly in systems.

    A structured approach helps you understand where estimates are being used, why they exist, and which assets or activities actually need attention. Scope 1 stops being a reporting distraction and starts becoming a practical lens on operational efficiency, maintenance and risk.


    If You’re an ESG or Sustainability Manager

    Scope 1 reporting is often where expectations are highest and tolerance for uncertainty is lowest.

    This is precisely why transparency matters. Clear assumptions, documented methodologies and visible confidence levels allow you to explain why estimates exist without undermining credibility. Instead of defending numbers, you can focus on improving them — and on using Scope 1 reporting to support reduction initiatives that are actually deliverable.


    If You’re a CFO or Finance Leader

    Scope 1 reporting is usually the most closely scrutinised because they sit closest to the organisation’s direct control.

    A disciplined approach ensures the numbers you sign off are consistent, explainable and governed — even when estimates are involved. More importantly, it gives you confidence that Scope 1 data reflects operational reality rather than accounting optimism.

    That’s what allows Scope 1 to stand up in board and assurance conversations.


    If You’re a CSO or Board Sponsor

    Scope 1 sets the tone.

    If an organisation can’t clearly explain its direct emissions — assumptions, estimates and all — confidence in the wider ESG story erodes quickly. A transparent, well-governed Scope 1 approach signals seriousness, maturity and control, even when data isn’t perfect.


    Bringing Scope 1 Into Focus

    Scope 1 reporting is often described as the “easy” scope. In reality, it’s simply the closest.

    It exposes gaps in data collection, inconsistencies in asset-level reporting, and assumptions that have quietly gone unchallenged for years. That discomfort isn’t a failure — it’s a signal.

    Organisations that treat Scope 1 as a managed discipline, rather than a static calculation, are better placed to improve accuracy, identify reduction opportunities and build confidence across their entire emissions profile.

    Scope 1 doesn’t need perfection.
    It needs clarity, ownership and progression.


    What This Looks Like in Horizon ESG reporting software

    Horizon ESG reporting software helps organisations bring structure and transparency to Scope 1 emissions without overcomplicating the process.

    Operational data, estimates and assumptions are made explicit. Confidence levels are visible. Improvements over time are trackable. Scope 1 emissions can be analysed by asset, activity or fuel type, allowing teams to focus effort where it genuinely matters.

    The result isn’t artificial precision — it’s decision-grade insight that stands up to scrutiny.


    The Horizon ESG View

    Scope 1 is where ESG credibility begins.

    Organisations that can explain their direct emissions clearly — including where estimates are used and why — find that conversations about Scope 2 and Scope 3 become markedly easier.

    That’s not because the data suddenly becomes perfect, but because trust has already been established – and the ESG reporting software highlights this.

    And in ESG, trust is the hardest thing to earn — and the easiest thing to lose. 

    Where Scope 1 Is Today — And Where It’s Heading Tomorrow

    From basic compliance to operational intelligence

    Where Scope 1 Reporting Is Today

    Today, scope 1 reporting is still largely treated as a compliance exercise. Many organisations rely on a mix of spreadsheets, manual meter readings, supplier invoices, and best-effort estimates pulled together at the end of the reporting cycle.

    Common characteristics we see:

    • Data collected after the fact, not as part of day-to-day operations

    • Heavy reliance on engineering assumptions or static emission factors

    • Limited audit trail explaining how numbers were calculated

    • Scope 1 treated as “simpler than Scope 3” — and therefore under-invested

    As a result, scope 1 data often lacks consistency, transparency, and confidence. Finance teams struggle to reconcile emissions with operational activity, sustainability teams spend time defending numbers instead of improving them, and reporting becomes reactive rather than strategic.

    In short: today’s scope 1 reporting tells you what happened, but rarely why — and almost never what to do next.


    Where Scope 1 Reporting Will Be Tomorrow

    Tomorrow, scope 1 reporting will be continuous, integrated, and decision-driven — powered by modern ESG reporting software rather than spreadsheets and manual workarounds.

    Forward-looking organisations are already moving towards:

    • Near-real-time data capture from operational systems, meters, and fuel sources

    • Clear lineage from activity data → calculation logic → reported emissions

    • Dynamic emission factors that update automatically as standards evolve

    • Scenario modelling to understand how operational changes affect emissions before they happen

    Crucially, scope 1 will no longer sit in isolation. It will be connected to planning, forecasting, and performance management — allowing teams to link emissions directly to cost, efficiency, and operational decisions.

    With the right ESG reporting software, scope 1 becomes:

    • Easier to explain to auditors

    • Easier to defend to the board

    • Easier to improve year on year

    The shift is subtle but important: scope 1 moves from reporting what you emitted to managing how you emit.

    For guidance on Scope 1 emissions see the GHG protocol Scope 1 document.

  • ESG Reporting Best Practices: 8 Proven Steps to Audit-Ready Disclosures

    ESG Reporting Best Practices: 8 Proven Steps to Audit-Ready Disclosures

    ESG reporting best practices — audit-ready disclosures

    Why ESG Reporting Best Practices Matter More Than Ever

    ESG reporting has matured rapidly. What was once a well-intentioned sustainability exercise has become a board-level, regulator-driven, investor-scrutinised discipline. With the CSRD now in force and assurance requirements expanding, organisations that lack structured ESG reporting processes face real consequences — delayed filings, qualified opinions, and eroded stakeholder trust.

    And yet, many organisations are still trying to meet modern ESG requirements using spreadsheets, disconnected tools, and heroic manual effort. The result? Reports that technically meet disclosure requirements, but fail to drive insight, confidence, or action.

    This article outlines eight ESG reporting best practices — not just to help you comply, but to help you manage, improve, and report with confidence. Whether you are preparing for your first CSRD submission or strengthening an existing programme, these practices will help your team deliver disclosures that stand up to scrutiny.


    1. Treat ESG Reporting as Performance Management — Not a Year-End Exercise

    Best practice
    Leading organisations manage ESG continuously, not annually. Targets are set, initiatives are planned, progress is tracked, and performance is reviewed throughout the year — just like financial performance.

    Real-world reality
    Many organisations still scramble to gather ESG data weeks before reporting deadlines. By then, it is too late to correct issues or explain unexpected results.

    What this means for you
    You stop firefighting at year-end and start steering outcomes throughout the year. ESG becomes something you actively manage — not something you nervously assemble at the last minute. A purpose-built ESG reporting platform makes continuous tracking practical by centralising data collection and automating reminders.


    2. Define Clear Scope, Boundaries, and Ownership from the Start

    Best practice
    Best-practice ESG reporting starts with absolute clarity:

    • What is in scope (and what is not)
    • Which entities, regions, and activities are included
    • Who owns each metric
    • How data flows, is reviewed, and approved

    Real-world reality
    Without clear ownership, ESG data often bounces between sustainability teams, finance, operations, and local sites — with no one fully accountable.

    What this means for you
    Fewer escalations, fewer surprises, and far less dependence on goodwill and last-minute heroics to get the numbers signed off.


    3. Design for Auditability — Even Before Assurance Is Mandatory

    Best practice
    High-quality ESG reporting includes full data lineage, transparent calculations, documented assumptions, and approval workflows — long before auditors formally arrive.

    Real-world reality
    As ESG assurance expands under CSRD requirements, many organisations discover their data cannot be traced back to source systems or clearly explained — leading to delays, rework, and uncomfortable conversations with assurance providers.

    What this means for you
    Confidence. When questions arise, you can explain exactly where numbers came from, how they were calculated, and why they are reliable.


    4. Use Technology Built for ESG Complexity (Because Spreadsheets Do Not Scale)

    Best practice
    Purpose-built ESG reporting software handles:

    • Multi-entity organisational structures
    • Scope 1, 2, and 3 emissions with automatic emission factor matching
    • Changing emission factors across reporting years
    • Multiple reporting frameworks (CSRD, GRI, CDP, TCFD) from one data model

    Real-world reality
    Spreadsheets break under ESG complexity — formulas drift, versions multiply, and confidence evaporates. When auditors ask how a number was calculated, the answer cannot be “it was in a spreadsheet someone emailed last March.”

    What this means for you
    You spend less time reconciling numbers and more time understanding trends, risks, and opportunities. See how Horizon ESG’s platform eliminates spreadsheet chaos.


    5. Be Transparent About Data Quality — and Improve It Systematically

    Best practice
    Best-practice organisations clearly distinguish between actual data, estimates, and AI-assisted estimates — and track improvements in data quality over time.

    Real-world reality
    Perfect ESG data rarely exists, especially for Scope 3. Pretending otherwise often damages credibility when assumptions are challenged during assurance.

    What this means for you
    Trust. Stakeholders — investors, auditors, and regulators alike — value honesty and progress far more than polished figures that cannot be defended.


    6. Link ESG Targets to Real Initiatives and Measurable Outcomes

    Best practice
    High-performing organisations link ESG targets directly to initiatives, investment decisions, and delivery milestones — not just disclosure metrics.

    Real-world reality
    Many ESG reports show ambitious targets, but cannot clearly explain how those targets will be achieved or what progress has been made against them.

    What this means for you
    You can clearly demonstrate how strategy turns into action — and how action delivers measurable results. This is particularly important under CSRD, which requires disclosure of transition plans and progress indicators.


    7. Use AI as an Accelerator — Not a Black Box

    Best practice
    AI-powered automation is used transparently to:

    • Fill data gaps with auditable, source-referenced estimates
    • Identify anomalies and flag data quality issues before auditors do
    • Support narrative reporting with structured first drafts
    • Match activity data to emission factors automatically
    • Guide teams with contextual insight based on their own data

    Human oversight remains firmly in place — AI accelerates the work, but every output is reviewed and approved by your team.

    Real-world reality
    Uncontrolled AI outputs raise more questions than they answer — especially with auditors and regulators who need to understand how disclosures were produced.

    What this means for you
    You gain speed and insight without losing control or credibility. Teams that previously spent twelve to sixteen weeks on reporting can complete the same work in four to six weeks.


    8. Build One ESG Data Foundation — Then Report Many Ways

    Best practice
    Leading organisations create a single ESG data backbone that supports:

    • Internal management reporting
    • Board updates and executive dashboards
    • Investor disclosures and ESG ratings questionnaires
    • Regulatory submissions (CSRD, CDP, GRI, TCFD)

    Real-world reality
    When ESG data is rebuilt separately for each audience, inconsistencies appear — and confidence erodes. An investor sees one number, the board sees another, and the regulator sees a third.

    What this means for you
    One version of the truth, fewer reconciliations, and a consistent ESG story everywhere it is told.


    How to Choose ESG Reporting Software That Supports Best Practices

    Implementing these ESG reporting best practices is significantly easier with the right technology. When evaluating audit-ready ESG reporting software, look for platforms that provide:

    • Centralised data collection — automated ingestion from ERP, HR, energy, and procurement systems
    • Full audit trail — every data point traceable to its source with change history
    • Multi-framework support — CSRD, GRI, CDP, TCFD, and ISSB from one data model
    • Carbon accounting — Scope 1, 2, and 3 with automatic emission factor matching
    • AI automation — intelligent gap-filling, anomaly detection, and narrative support
    • Workflow management — role-based access, approval chains, and deadline tracking
    • Scalable pricing — transparent pricing that grows with your organisation

    For a side-by-side view of what to look for, see our guide to the best ESG reporting software in 2026.


    Final Thought

    The strongest ESG leaders do not just report well — they manage well.
    When ESG reporting follows best practice, it becomes a source of confidence, control, and strategic advantage — not just another regulatory obligation. Book a demo to see how Horizon ESG puts these best practices into action.


    Frequently Asked Questions

    What are ESG reporting best practices?

    ESG reporting best practices are proven approaches that help organisations produce accurate, audit-ready sustainability disclosures. They include establishing clear data ownership, designing for auditability, using purpose-built ESG software, being transparent about data quality, and leveraging AI to accelerate reporting without losing control.

    What software do I need for ESG reporting?

    You need a purpose-built ESG reporting platform that handles multi-entity data collection, carbon accounting across all scopes, multiple reporting frameworks from one data model, and full audit trails. Spreadsheets do not scale for organisations reporting under CSRD, GRI, or CDP simultaneously.

    How do I prepare for CSRD reporting?

    Start by defining your reporting scope and conducting a double materiality assessment. Establish data ownership for every metric, ensure your systems can produce auditable data trails, and build processes for continuous data collection rather than year-end scrambles. Purpose-built ESG software significantly reduces the effort required.

    Can AI help with ESG reporting?

    Yes. AI-powered ESG tools can automate data collection, match activity data to emission factors, detect anomalies, fill data gaps with auditable estimates, and draft narrative disclosures. The key best practice is to keep humans in the loop — AI accelerates the work, but your team reviews and approves every output.

    How long does ESG reporting take?

    Without automation, a full ESG reporting cycle typically takes twelve to sixteen weeks. Organisations using AI-powered ESG reporting software can reduce this to four to six weeks by automating data collection, emission factor matching, and validation — freeing teams to focus on analysis and strategy rather than data wrangling.

Book Your Free Demo